Personal Finance Tips to Build Wealth in 2026 (A Beginner’s Roadmap)
Building wealth is not about luck or a surprise windfall — it is about repeating a few smart decisions until they compound. These personal finance tips focus on the long game: growing your net worth steadily through 2026 with habits that work on any income. If you want more than just a tidy budget, this roadmap is for you.
We will move beyond the basics of spending less and into the strategies that actually create financial freedom: raising your income, investing with intention, and protecting the wealth you build.
Shift your mindset from spending to net worth
Most people measure money by what is in their checking account today. Wealth builders track net worth instead — assets minus liabilities. This single mental shift changes every decision, because you start asking whether a purchase grows or shrinks your long-term position.
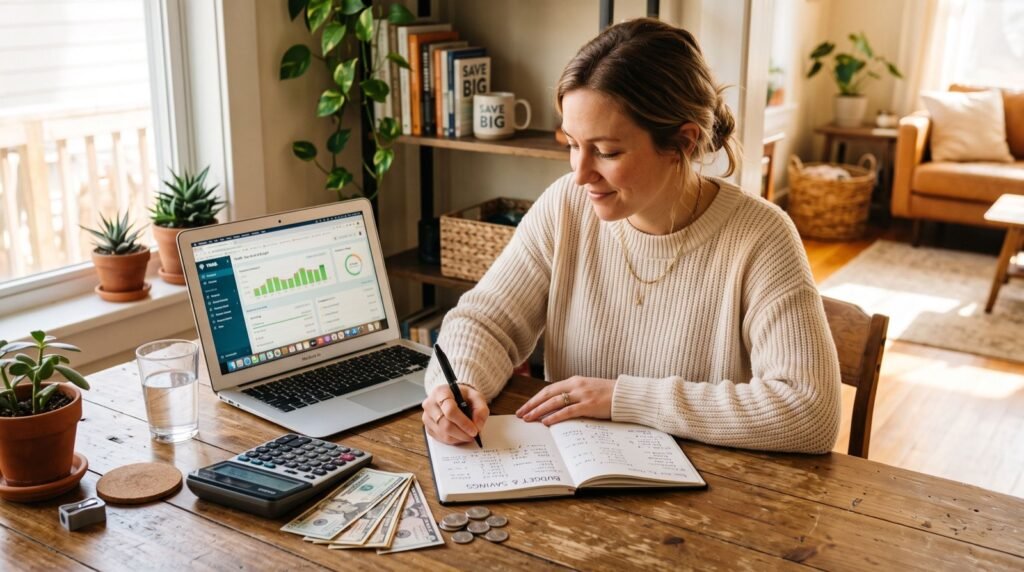
Calculate your net worth once a month. Watching that number climb, even slowly, is far more motivating than staring at a restrictive budget.
Personal finance tips that raise your income
You can only cut expenses so far, but your earning potential has real room to grow. The fastest path to wealth usually runs through a bigger income, not a smaller latte budget.
- Negotiate your salary — even a 5% raise compounds over a career.
- Build a marketable skill that commands higher pay.
- Start a low-cost side hustle using tools you already own.
- Turn a hobby into freelance income on evenings or weekends.
For a broader collection of habits that pair income growth with disciplined saving, these personal finance tips are a practical starting point.
Invest consistently and let compounding work
Time in the market beats timing the market. According to the U.S. Securities and Exchange Commission’s compound interest resources, modest, regular contributions can grow dramatically over decades thanks to reinvested returns.
Automate contributions to a retirement account and a low-cost index fund. If your employer matches a 401(k), contribute at least enough to capture the full match — it is free money you should never leave on the table.
How much should you invest each month?
A common target is 15% of gross income toward retirement and long-term goals. If that feels out of reach, start at 3% and raise it by 1% every time you get a raise. You will barely notice the difference in take-home pay.
Compare wealth-building accounts in 2026
| Account | Main benefit | Ideal goal |
|---|---|---|
| 401(k) with match | Free employer contributions | Retirement |
| Roth IRA | Tax-free withdrawals later | Long-term growth |
| Brokerage account | Full flexibility | Mid-term goals |
| High-yield savings | Liquidity and safety | Emergency fund |
Each account plays a different role. Used together, they form a layered system that balances growth, flexibility, and safety.
Automate your money with the right tools
Automation removes the willpower problem entirely. Set up automatic transfers so saving and investing happen before you can spend the money. Many of the best money apps now handle round-ups, recurring investments, and bill tracking in one place, making the whole system run quietly in the background.
The goal is a financial life that works even when you forget about it. Set it once, review it monthly, and adjust as your income grows.
Avoid the lifestyle creep trap
Lifestyle creep is the quiet enemy of wealth. As income rises, spending tends to rise right alongside it — a bigger apartment, a nicer car, pricier habits — leaving net worth exactly where it started. The antidote is to bank your raises before they reach your spending.
Each time you earn more, immediately direct at least half of the extra income to savings or investments. You still enjoy a lifestyle upgrade with the other half, but your future self captures real progress too. This single habit separates high earners who build wealth from those who simply spend more.
The same discipline applies to windfalls. Tax refunds, bonuses, and gifts feel like free money, which makes them easy to blow. Treat them instead as rocket fuel: send the bulk straight into your goals and allow yourself a small, guilt-free reward from the rest.
Build multiple income streams
Relying on a single paycheck is risky, and the wealthiest households rarely do. Over time, aim to develop two or three income streams so a job loss never derails your plans. Dividend-paying investments, a side business, or rental income all diversify where your money comes from.
You do not need to launch everything at once. Add one additional stream per year, start small, and reinvest the early earnings to help it grow. Patience compounds here just as powerfully as it does in the market.
Protect the wealth you build
Growing money is only half the job; keeping it is the other half. Adequate insurance, an up-to-date will, and a healthy emergency fund guard your progress against setbacks. One uninsured disaster can erase years of careful saving.
Review your coverage annually. As your assets grow, your protection should grow with them.
Know when to call in a professional
DIY works for most everyday money moves, but complex situations deserve expert eyes. When the stakes are high and the details are fragile — think estate planning or a major tax event — bring in qualified help the same way you would trust dependable specialists with your most valuable possessions. A fee-only financial planner can save you far more than their cost.
Frequently Asked Questions
What are the best personal finance tips for building wealth fast?
Focus on raising your income, investing the difference automatically, and avoiding high-interest debt. Wealth compounds fastest when you widen the gap between what you earn and what you spend.
How much money do I need to start investing?
You can start with as little as $5 using fractional shares. Consistency matters far more than the starting amount, so begin now rather than waiting for a “perfect” lump sum.
Is it better to pay off debt or invest first?
Pay off high-interest debt above roughly 7% first, since few investments reliably beat that. Below that threshold, investing while paying down debt can make sense, especially to capture a 401(k) match.
How do I stay motivated to build wealth?
Track your net worth monthly and set specific, meaningful goals. Watching the number rise turns an abstract habit into a visible, rewarding game.
Final thoughts: wealth is a habit, not an event
The most powerful personal finance tips are unglamorous: earn more, automate your saving, invest consistently, and protect what you build. Repeat those four moves through 2026 and beyond, and compounding does the rest.
Pick one action from this roadmap and complete it today. Wealth is built one deliberate decision at a time, and your first decision starts now.